Mortgage lenders now have more credit score options. What to know Skip Navigation Markets Pre-Markets U.S. Markets Europe Markets China Markets Asia Markets World Markets Currencies Prediction Markets Cryptocurrency Futures & Commodities Bonds Funds & ETFs Business Economy Finance Health & Science Media Real Estate Energy Climate Transportation Investigations Industrials Retail Wealth Sports Life Small Business Investing Personal Finance Fintech Financial Advisors Options Action ETF Street Buffett Archive Earnings Trader Talk Tech Cybersecurity AIEnterprise Internet Media Mobile Social Media CNBC Disruptor 50Tech Guide Politics & Policy White House Policy Defense Congress Expanding Opportunity Europe Politics China Politics Asia Politics World Politics Video Latest Video Full Episodes Livestream Top Video Live Audio Europe TVAsia TVCNBC Podcasts CEO Interviews Digital Originals Watchlist Investing Club Trust Portfolio Analysis Trade Alerts Meeting Videos Homestretch Jim's Columns Education Subscribe PROPro News Josh Brown Mike Santoli Calls of the Day My Portfolio Livestream Full Episodes Stock Screener Market Forecast Options Investing Chart Investing Subscribe Livestream Menu Make Itselect USAINTLLivestream Search quotes, news & videos Livestream Watchlist SIGN INCreate free account Markets Business Investing Tech Politics & Policy Video Watchlist Investing Club PROLivestream Menu Personal Finance Mortgage lenders now have more credit score options.
Key Takeaways & Highlights
- Mortgage lenders now have more credit score options.
- What to know Skip Navigation Markets Pre-Markets U.S.
- The FHFA oversees Fannie Mae and Freddie Mac.
Key Background and Context
What homebuyers should know Published Tue, May 5 20268:15 AM EDTUpdated Tue, May 5 20268:33 AM EDTSarah Agostino WATCH LIVEKey Points Mortgage lenders can now use Vantage Score 4.0 and will eventually be able to use FICO 10T — both of which consider rent and utility payments, if that information is available.A "classic" FICO score, the only one previously approved for use in mortgage underwriting for loans sold to Fannie Mae and Freddie Mac, does not factor in that history.The newer credit score models also consider "trended data" — which basically looks at your credit behavior over a period of time, usually 24 months.In this article EXPN-GBFollow your favorite stocks CREATE FREE ACCOUNTCatherine Delahaye | Getty There's a shift going on with credit scores in the homebuying process that consumers may want to be aware of.Mortgage lenders are now permitted to use a credit score called Vantage Score 4.0 as part of their underwriting process instead of a "classic" FICO score, which has been the only approved score for decades, government officials announced April 22.
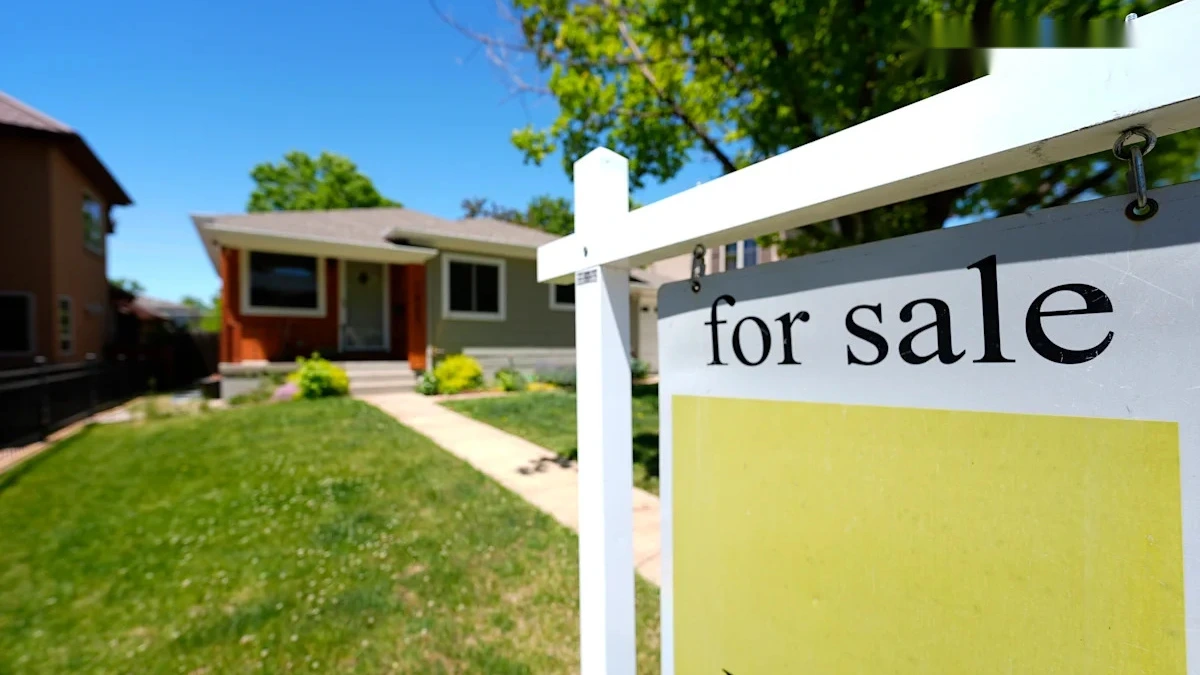
At some point in the coming months, another alternative score, FICO 10T, will also be permitted.The change applies to mortgages sold to Fannie Mae and Freddie Mac, government-sponsored enterprises that are the largest purchasers of mortgages on the secondary market. Additionally, the Federal Housing Administration, which insures many loans for first-time buyers, also will soon use these two scores, Housing and Urban Development Secretary Scott Turner said during a press conference announcing the changes.

Latest Developments and Impact Analysis
HUD oversees the FHA.Read more CNBC personal finance coverage Market sell-off hits hard: Advisors say 'stay the course with an eye on buying'IRS announces new federal income tax brackets for 2027These states are offering extra ACA premium subsidies in 2027CNBC's Financial Advisor 100: Best financial advisors, top firms for 2026 ranked CNBC Elite Advisors: Top ultra-high net worth wealth management firms for 2026Twenty-one large mortgage lenders are part of the first wave that will use Vantage Score 4.0, Federal Housing Finance Agency Director Bill Pulte said during the press conference.
The FHFA oversees Fannie Mae and Freddie Mac. Pulte also said Freddie Mac has already taken $10 million in loans approved using Vantage Score 4.0.The significance of the changes for consumers is that these two alternative credit scores use data points that a classic FICO score doesn't consider.
While lenders may still use the classic FICO score, they will have a choice in which scores to use — and the newer models could help some consumers qualify for a mortgage or get a better rate.Here's what to know.Rent, utility payments count — if they get reported A notable difference between a classic FICO score and the approved newer models is the potential inclusion of a consumer's history of paying rent and utilities.The idea is that some consumers may consistently pay those bills on time, and their score could benefit from that — especially if they don't have much on their credit report, such as credit cards or an installment loan, for instance."How can you not have credit scores include a major factor in the past payment history of somebody with rent?" Pulte said during the press conference.
"That's highly predictive."watch now VIDEO0:3100:31Can you afford to buy a home?Personal Finance However, a score that factors in rent history or utility payments has to receive that information, and experts say most renters' data is not making its way to the credit bureaus for use in any score."Just because you're renting an apartment doesn't mean it's being reported to any credit bureau," said John Ulzheimer, a credit expert and president of The Ulzheimer Group in Atlanta.Currently, Vantage Score models capture only rent or utility payment data that consumers opt in to have reported to the three largest credit reporting companies, Equifax, Experian and Trans Union, according to a spokesperson for Vantage Score.Just because you're renting an apartment doesn't mean it's being reported to any credit bureau.John Ulzheimer President of The Ulzheimer Group Some property managers use software to feed data to one or more credit bureaus.
Renters may also sign up for a rent-reporting service that will pass the information along, Ulzheimer said. Those services may come with a monthly fee of $10 or so, although some large property managers use such a service and may provide it for free to renters who want to participate.The share of consumers whose rent payments are reported to credit reporting agencies rose to 13% last year from 11% in 2024, according to a Trans Union report that was based on a survey of 2,006 adults in March 2025.There are about 46.4 million renter-occupied households in the U.S., according to the Federal Reserve Bank of St.
Louis.Trended data may help or hurt your score There's another metric that is used in the new models and generally is already available to the credit bureaus: so-called trended data.In simple terms, trended data is based on your credit behavior over time — typically the last 24 months.
For instance, your credit card company typically reports your balance, the minimum monthly payment required, and the actual payments made over that stretch of time to the credit bureaus, Ulzheimer said."That's instead of just a snapshot of a balance in the last month," he said.While trended data is already included in consumer credit reports, it has not been incorporated into the classic FICO score used in mortgages, Ulzheimer said.
This information is valuable, he said, in determining who is a "transactor" — a credit card user who routinely pays off their balance — and who is a "revolver" — someone who carries a balance from month to month, which can be a riskier borrower for a lender."They can look identical based on a credit score, but they have very different risk," Ulzheimer said.
Because the classic FICO score is based on a snapshot instead of trended data, some mortgage borrowers have been able to fairly quickly bring their score up ahead of applying."It used to be that you pull your credit report [a couple months] ahead of applying and try to pay down your credit cards as much as possible," Ulzheimer said.Doing so generally has meant your FICO score would get a boost, and that number is what lenders would see.
Now, if Vantage Score 4.0 or FICO 10T is used, some consumers may want to think about their credit score far ahead of applying for a mortgage, Ulzheimer said."You'll have to do a better job of managing your credit card debt over time, not just a month or two before you put in a mortgage application," Ulzeimer said.Choose CNBC as your preferred source on Google and never miss a moment from the most trusted name in business news.
Comments 0
Leave a Comment
No comments yet. Be the first to share your thoughts!