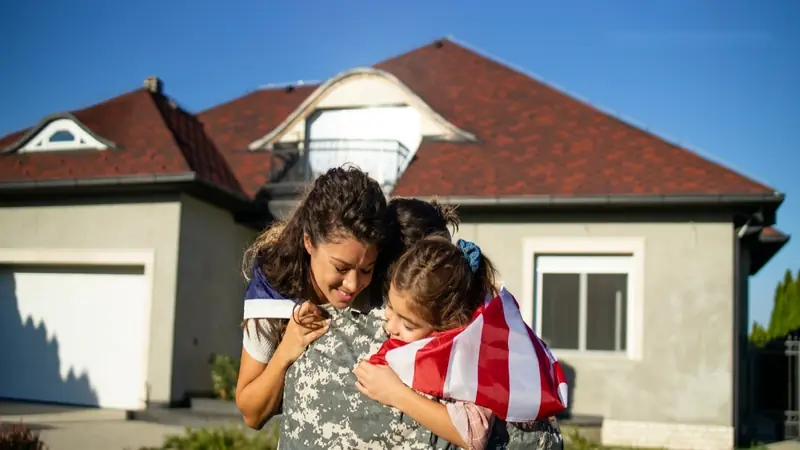
In the latest development regarding military spouse’s advice, During my husband’s active duty, our family lived in five different states. We packed up our belongings 10 times, rented several homes and purchased two. We learned how to settle into a new place quickly, but making a house feel permanent was another matter.
Key Takeaways & Highlights
- During my husband’s active duty, our family lived in five different states.
- We packed up our belongings 10 times, rented several homes and purchased two.
- It was difficult to feel connected to our neighbors and community when we knew we would eventually have to start over.
Key Background and Context
Knowing another move was likely around the corner, we sometimes questioned whether decorating, or even unpacking, was worth the effort. It was difficult to feel connected to our neighbors and community when we knew we would eventually have to start over.
That repeated disruption is familiar to many military families. According to the Military Family Advisory Network, military families move, on average, every 2.5 years.

Latest Developments and Impact Analysis
Supporting families after they settle in
After more than two decades as a military spouse and, more recently, a veteran spouse, I know that finding a home is only one part of the transition from military to civilian life. A veteran may be looking for civilian work while learning to live with service-related health challenges. Their spouse may be rebuilding a career interrupted by repeated moves. Children have their own adjustments to make.
As mortgage professionals, we often meet families during this transition and have a window into some of the pressures and uncertainty they might be facing. As part of our mission of making home happen, we can also help our organizations and colleagues understand some of the unique circumstances surrounding these families and where we can collectively provide more assistance.
In August 2025, 5.8 million veterans, or 34% of all U.S. veterans, had a service-connected disability, according to the Bureau of Labor Statistics. For some families, access to health care may be a pressing concern. Others may need help finding work or support for a spouse or child. Mortgage lenders and other employers can contribute through organizations equipped to address those needs.
Begin by getting to know the organizations already serving military families. For example, Camp Hope provides a residential program addressing combat-related trauma, along with support for families, at no cost. Stronghold Food Pantry provides free food assistance to military families, while In Dependent Wellness offers wellness resources and programs for military spouses.
Ask these organizations where support is most needed before deciding what to offer. Some organizations may benefit most from a financial contribution; others may need volunteers or help reaching families who could use their services.
Employers have opportunities within their own workplaces, too. They can take action by investing in training and career opportunities for transitioning service members and veterans. The Department of War (Do W) Skill Bridge program offers industry training and work experience to service members with 180 days or fewer remaining before military discharge.
Becoming a program provider is one way an employer can help service members prepare for civilian careers. Employee resource groups can also give veterans a place to connect with colleagues and help others understand their experiences.
Know the benefit and the borrower
The VA home loan benefit gives eligible veterans an important financing option. According to the National Association of REALTORS®, 55% of veteran homebuyers in 2025 used VA financing. Helping a family evaluate that option requires mortgage professionals who know the program well enough to explain how it applies to their circumstances.
That requires ongoing education for loan officers and broker partners. For example, mortgage professionals should understand that the benefit is not limited to one use and that eligible borrowers may qualify for another VA-backed loan while an existing one remains active.
Lenders can put that education into practice through regular in-person or virtual training and digital resources that address program requirements and borrower questions. Mortgage originators should take advantage of those resources and guidance from the VA, rather than rely on assumptions about who can qualify. A thorough understanding of the program can help them identify options they might otherwise overlook.
The conversation should begin with a question about whether the borrower has served. From there, ask what is prompting the move and how the purchase fits their finances. Take time to understand what the family needs from the home and whether the payments will be manageable. Evaluate VA financing alongside other appropriate options so the borrower can make an informed choice.
Remember, home is where families finally get to breathe
For veterans and their families transitioning to civilian life, a permanent home can mean an end to planning around the next move. It offers the chance to build lasting connections with neighbors and become part of a community.
For our family, my husband’s service-connected disabilities and our son’s special needs have made a stable home especially important as we adjust to life after the military. I know how much it means to finally have a place where you can unpack everything, settle in and make a home your own. Finding the additional support our family needs has been part of that adjustment, too.
A commitment for this Veterans Day
I still think about those moving boxes and all the times our family had to begin again. This Veterans Day, it’s my hope that employers will look at how they support military families in their communities and workplaces. Mortgage professionals can examine whether their knowledge is keeping pace with the needs of the borrowers they serve.
For those working with borrowers, one place to start is a 30-minute commitment: Study one VA guideline you don’t fully understand and learn about one aspect of military family life. Make that a starting point for ongoing learning about both the benefit and the people who use it.
Our family needed a home we could settle into. We also needed people who understood what we were adjusting to. We owe it to veterans and their families to learn about the challenges they face after military service. To honor their service to our country, we as individuals and organizations should take every opportunity to serve them too.
Brittany Boccher is the Newrez National Director of Military Strategy & Military Engagement.This column does not necessarily reflect the opinion of Housing Wire’s editorial department and its owners. To contact the editor responsible for this piece: [email protected].
Related
More: Mortgage Servicing VA Loan
Comments 0
Leave a Comment
No comments yet. Be the first to share your thoughts!